
The debt collection sector, and the judicial officer in particular, is in a transitional phase. While traditional activities such as seizures and the serving of judgments have historically defined the image, the core of the profession is shifting rapidly. It is increasingly about offering genuine perspective to the customer (debtor). In the complex and challenging social context in which we live, it is essential to offer a helping hand early on, prevent further escalation, and facilitate the path to appropriate assistance.
This people-oriented approach is not at odds with the client’s interests; rather, it strengthens them by preventing reputational damage, maintaining customer relationships, and providing proactive advice. All of this requires a fundamentally different, future-proof business model. Bosveld Judicial Officers & Debt Collection has begun this transition over the past two years, with the IBO report on Problematic Debts serving as an important starting point.
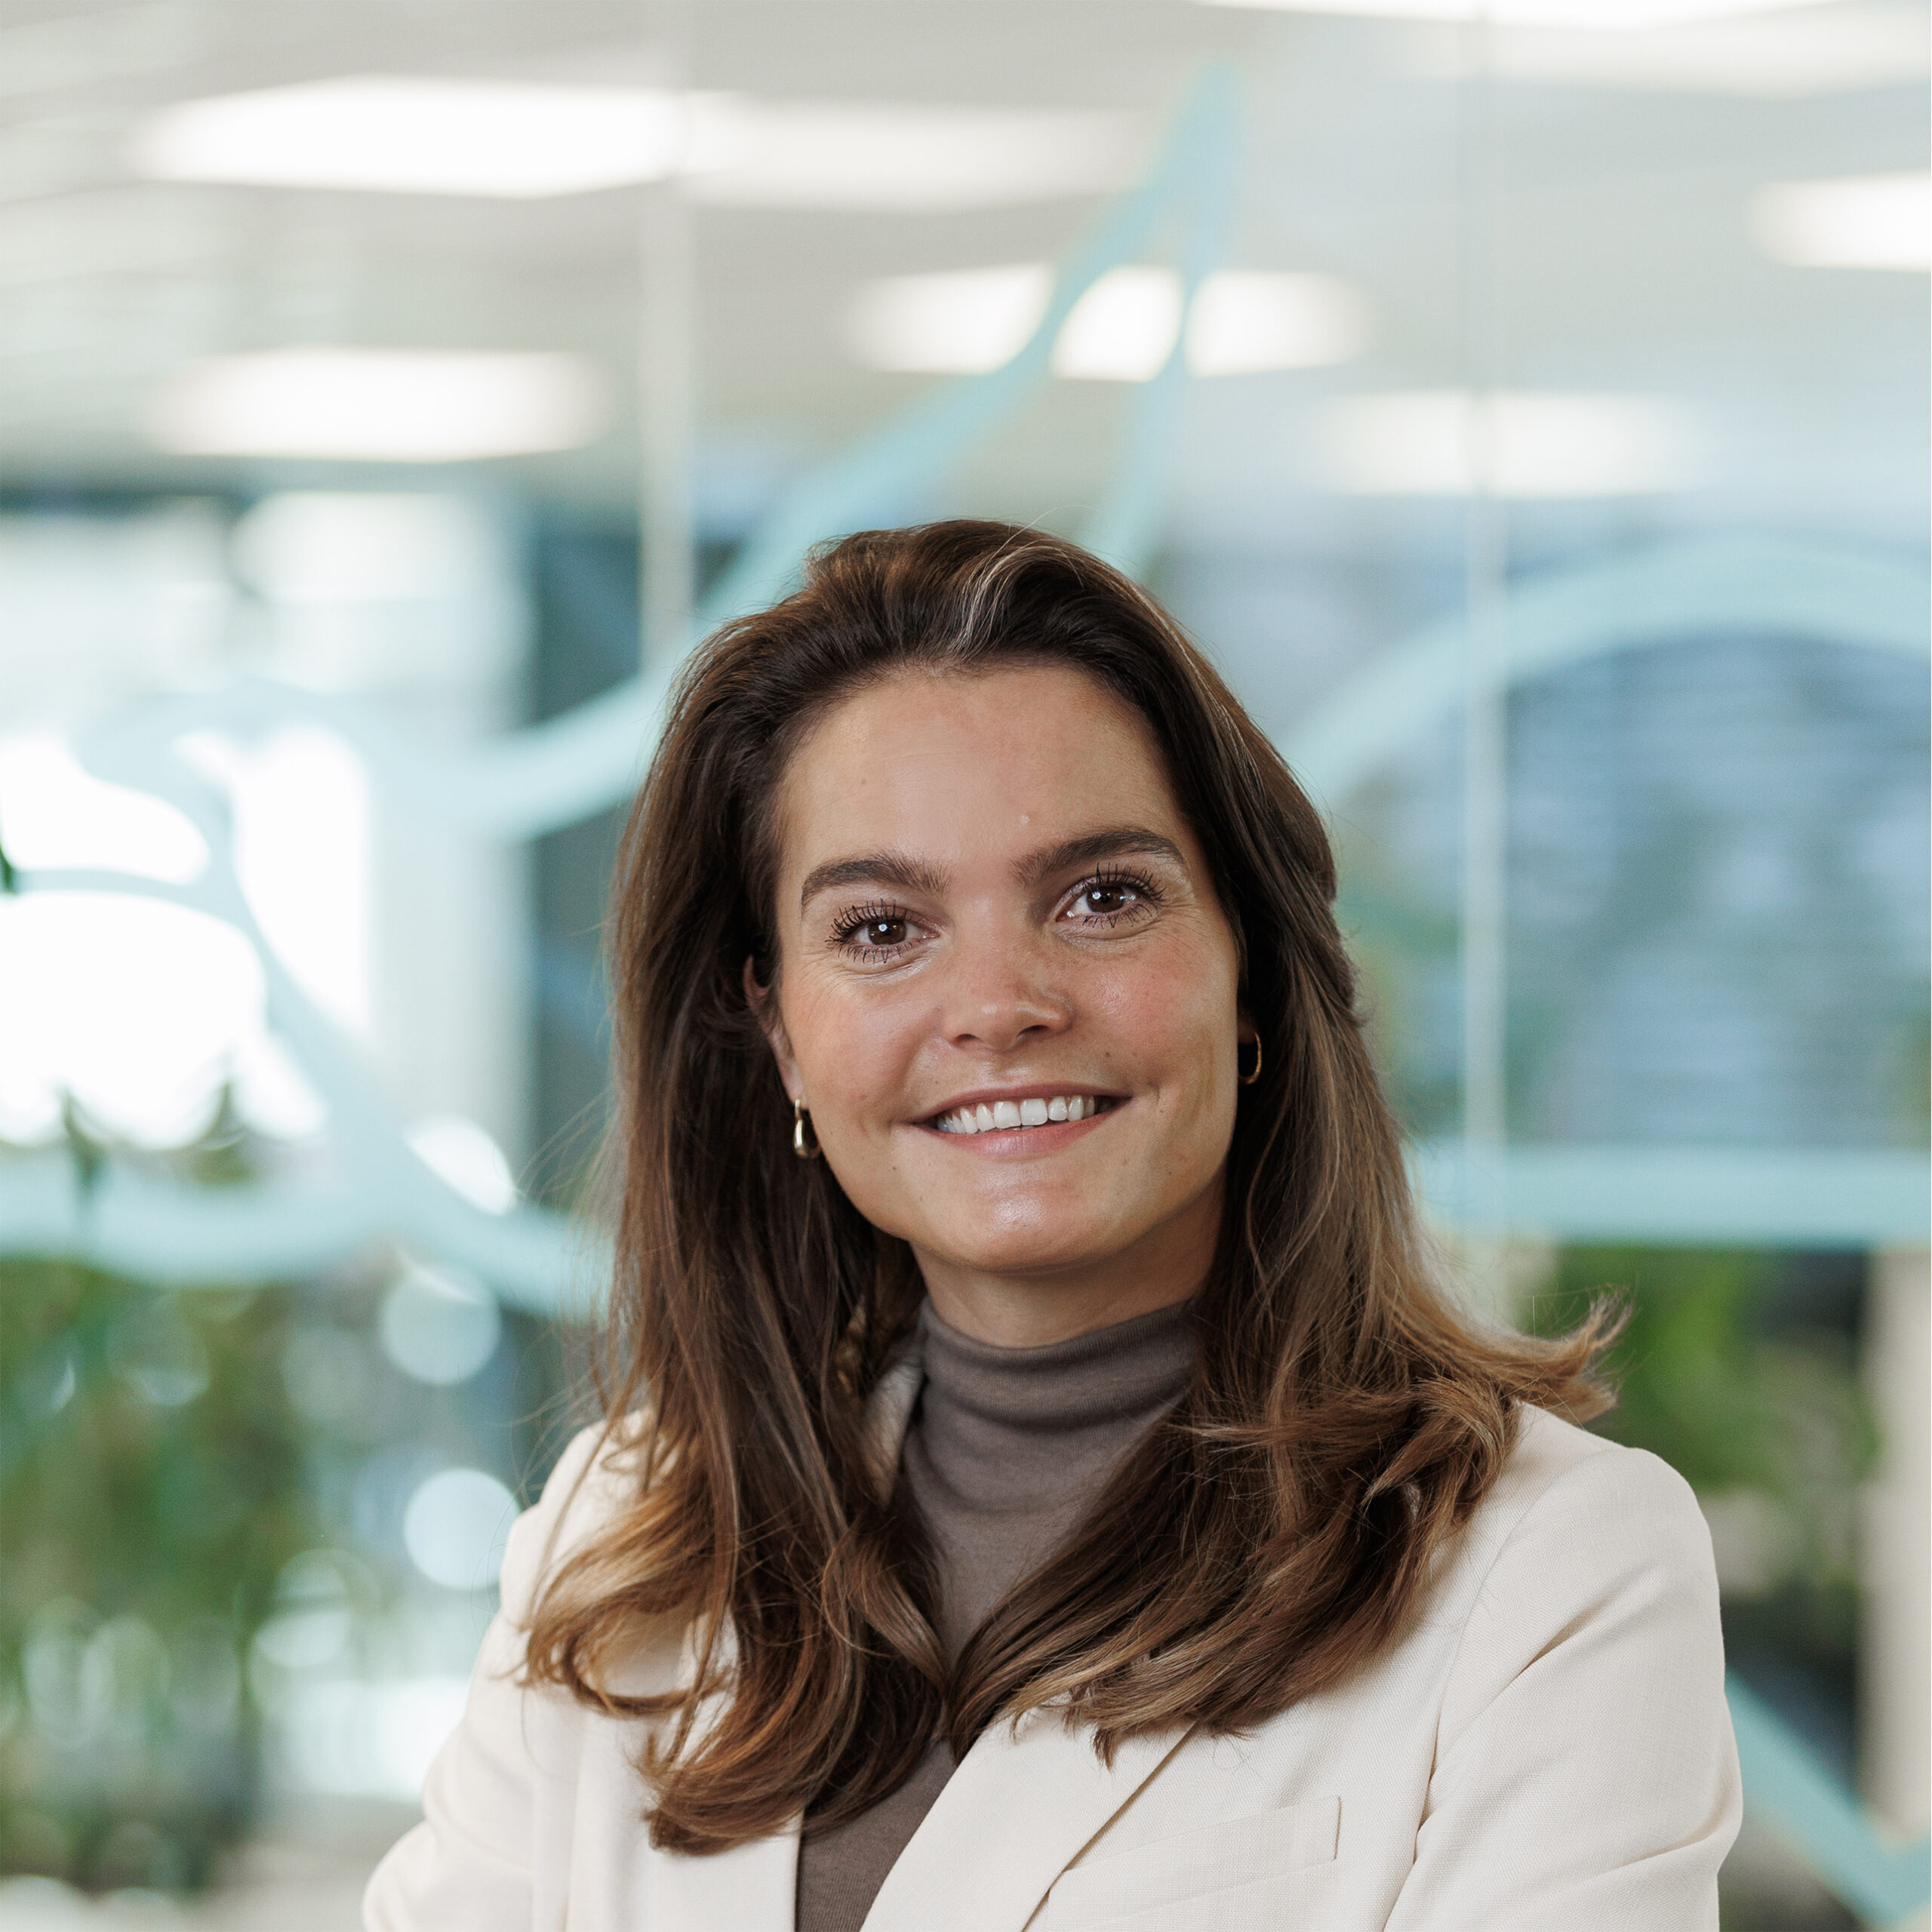
This year, the management team at Bosveld was strengthened by Emma Weber, who will further shape this course as Commercial Director. In this candid interview, I speak with Emma about her first impressions of the sector. She shares her striking transition from the international wine world, her perspective as an ‘outsider,’ and her ambition to truly connect social and commercial interests.
Can you tell us something about yourself? What are important aspects of business life for you?
Emma: “Before I started at Bosveld, I worked for over seven years for a large international wine organization. As the person ultimately responsible for commercial affairs, I was part of the management team and determined the commercial course. I led a team of driven professionals and translated organizational goals into clear commercial choices and concrete execution in the market. A significant part of my role involved building and deepening strategic partnerships: understanding what our clients wanted to achieve, how their organization functioned, and where our knowledge and expertise could truly add value. Always in a way that aligned with their identity, ambitions, and daily practice.
Parallel to my work, I completed a Master’s in Business Sales. There, I learned through design thinking to look more broadly at value creation: not just from the perspective of the organization itself, but also from the customer and the context in which they operate. That requires an eye for the interests, needs, and interdependencies of the various stakeholders within the ecosystem.
That way of thinking has enriched my view of commerce. Financial results remain important, but they are not the only criterion for success. For me, value creation is about finding a shared ambition, even when interests seem to diverge at first glance. Co-creation helps to bring different perspectives together and arrive at solutions that are valuable for clients, suppliers, employees, and society.
I put that vision into practice in my Master’s research. I investigated alcohol abuse and the responsibility the alcohol industry itself can take to reduce it. In doing so, I deliberately looked beyond the sector alone: at how individuals, organizations, the industry, and society can each contribute from their own role. What struck me most was how differently involved parties view the same issue and how little those perspectives sometimes align.
That is precisely where the value of open dialogue lies for me. Not to eliminate differences, but to make them discussable and to search for what does connect parties. By placing interests, beliefs, and experiences side by side, more understanding is created for the issue and for each other’s positions. From there, you can take concrete steps together. That research further sharpened my conviction: even as a commercial organization, you bear a responsibility that goes beyond your own results. I bring that way of thinking and working with me to Bosveld.”
How did you end up at Bosveld? After all, it is quite a big step from the wine world to debt collection and judicial enforcement. What was the deciding factor for you to make this move?
Emma: “Great question! And by now, it’s almost standard during a first introduction. At first glance, the wine world and the debt collection and judicial officer industry are quite far apart. Yet the transition felt surprisingly logical to me.
What I take from the wine and hospitality sector is that good service begins with genuine attention. Not just looking at what you deliver, but especially understanding who is sitting across from you and what that person needs. I also bring that thought to this sector. Whether it concerns a client or someone with a payment arrears: you achieve more if you understand what is going on and tailor your approach accordingly.
What ultimately attracted me to Bosveld was the complexity of the profession. This is where social responsibility, commercial interests, laws and regulations, and very personal situations come together. Additionally, the sector is changing rapidly, and with it, the role of the judicial officer. The expectations of clients and society are shifting, while financial pressure and temptations increase, and the room to absorb setbacks is shrinking for many people. That makes early action increasingly important.
I see the fact that I come from outside the sector as an advantage. I look at existing working methods without fixed assumptions and do not automatically assume that something is good just because we have always done it that way. Not to change everything for the sake of change, but to stay sharp on what can be improved. That is precisely why Bosveld is a logical next step for me.”
I find it refreshing and positive, but I am also curious how (potential) clients and partners react to your ideas?
Emma: “I mainly notice a lot of curiosity and willingness to engage in conversation. I deliberately used my first period to get to know clients, potential chain partners, other judicial officer firms, and debt collection parties. People really take the time to share their knowledge and experiences and to guide me through the different sides of the profession. I appreciate that enormously.
Among clients, I notice a lot of attention to image, brand preservation, and customer relationships. The ambition to collect socially is great, but practice requires careful choices. After all, these are sensitive situations, and even within the judiciary, emphases are placed differently. This means that many clients are looking for an approach that is legally sound, fits their organization, and does justice to their customer.
Within debt collection, automation, data, and digitalization are meanwhile creating new possibilities, but they also put pressure on existing working methods and business models. That requires conscious choices about where technology helps and where personal contact and human judgment remain necessary. I see an important role for the judicial officer in exactly that. They combine legal powers with personal contact and insight into what lies behind a payment arrears. Developments regarding the Collective Repayment Plan and the duty of care emphasize that broader role within the debt chain.
What also strikes me is the openness among social chain partners involved in debt and financial health. From their role, they sometimes view judicial officer firms and debt collection parties very differently than we do ourselves. That is precisely why I find it valuable that the willingness to cooperate is so great. Not from a place of distrust or by opposing each other, but from a shared ambition to better tackle debt problems.
At the same time, I notice that the market is clearly waiting in some areas. Many developments have been announced or are already underway, but the practical consequences are not yet clear everywhere. Parties are preparing, but at the same time waiting for more clarity from the government, legislation, and the judiciary before they truly make choices. That tension between wanting to move and not yet knowing exactly what is coming is clearly palpable at the moment.
What would you like to achieve? When will your mission be successful?
Emma: “That’s a good one. My mission will be successful if we manage to develop a business model in which the interests of the client, the customer, and society are much more aligned. A model that not only creates value when a file reaches us, but especially before that.
That means we better enable clients to improve their own processes, signal payment problems earlier, and where possible, prevent a file from having to flow through to a debt collection or judicial officer firm at all. And if it is necessary, we must deploy the right intervention as early as possible to prevent further escalation and restore positive payment behavior.
For me, that is the core of a future-proof business model. Not the number of files, but what our approach yields should be leading. If we can make that visible and measurable and build a financially healthy model around it that increases social benefits, then in my view, we have truly achieved something.”
I find that an interesting approach. How would you translate the benefits, seen from the perspective of the judicial officer?
Emma: “I find the social benefits very important, and there is rightly a lot of attention for them. What is also becoming increasingly interesting to me is what value a careful approach can also yield for the client.
A file is not just an outstanding claim, but also the endpoint of a customer journey. It tells a lot about what preceded it. By combining file data with insights from contact moments and behavior, you get a better view of where customers drop off, which communication leads to action, and when a different approach is more effective.
In doing so, I find it important to look beyond just what someone does. People also differ in the way they process information and what helps them to take action. One person has more need for overview and clarity, another for freedom of choice, extra explanation, or personal contact. By connecting those behavioral insights with factual file information and what we see in contact moments, you can design the customer journey much more purposefully. The legal position does not change, but the way you communicate and seek contact can be better aligned.
You can bring that knowledge back to the client. Not just reporting how many files have flowed in and what has been paid, but showing what those files tell us about the preceding trajectory. With that, you can together refine the customer journey in a way that is legally careful, understandable for the customer, and fits the identity and working method of the client. I find that last part particularly important: our approach must align with how our client wants to treat their customers.
And if that leads to fewer files unnecessarily ending up with a judicial officer, I consider that a win. If our involvement is necessary, we know better what preceded it and can act more purposefully. For me, a significant part of the value that Bosveld can add lies there: combining legal expertise with data, behavioral insights, and practical experience, and using that knowledge to help clients continuously improve their customer journey.”
Within this framework, how do you see the future role of the judicial officer? A financial-social advisor or a guardian of the law? Or both?
Emma: “For me, it’s not an either-or. The judicial officer has a special position within our legal system, with statutory powers and an independent responsibility. At the same time, more and more is expected of the judicial officer. You can also see this reflected in the WODC research Serving and Earning: The Future-Proofness of Judicial Officers. In it, law enforcement and the protection of people with debts emphatically come together. Developments regarding the Collective Repayment Plan, the Government Debt Collection Vision, and the duty of care also point in the same direction. The social role of the judicial officer is broadening, while the organization and financing of it do not always move at the same pace.
Our value lies less and less solely in performing an official act. We possess legal knowledge, but in practice, we also see what happens when payment is not forthcoming, where situations get stuck, and which approach does or does not work. That combination helps us to recognize earlier what is needed and to advise clients more purposefully on that.
That doesn’t mean we should want to do everything ourselves. Debt counseling and social support require different knowledge and responsibilities. For me, cooperation means very concretely that you recognize in time when someone needs other help, know which party can assist with that, and ensure that the transfer actually takes place.
I therefore see the judicial officer of the future as a professional with a clear official task and a broader role alongside it. Not only acting when an official act is required, but also adding value for the client and customer earlier in the process.
This also includes a realistic conversation about financing. If we expect more from judicial officers than just official acts, we must also look at how that broader role is valued and paid for.”
Whichever way we look at it, who is ultimately going to pay the costs?
Emma: “The costs must be paid somewhere; we cannot get around that. But I find that we too often only look at where those costs are incurred, and too little at where the benefits ultimately accrue.
If our service, for example, prevents problems from escalating further, enables clients to improve their processes, or limits social costs, then that value does not always arise with the same party that makes the investment. And that is precisely where an important question lies for me: if the benefits accrue elsewhere, it is also logical to look at whether a portion of the costs can be placed there.
In short: the costs must be paid, but we must look much better at where the benefits accrue and who profits from them. That requires a different conversation about how we value and finance our services. Precisely that conversation is what I find interesting, and that is what I am committed to.”
What can visitors to Credit Expo expect from you?
Emma: “This year as well, during Credit Expo, we are putting a topic on the table that is allowed to be a bit provocative. Together with Michiel Vos, we look at America, credit, and the rise of mass claims.
America shows what can happen when lending, debt, and consumer protection get out of balance. The question is how far we in the Netherlands really are from that.
Here too, we see tensions arising. Consumer protection rightly receives a lot of attention, while clients simultaneously have to deal with changing case law, new risks, and increasingly high expectations. Mass claims make that field of tension visible, but for us, they are primarily the starting point for a broader discussion.
During Credit Expo, we want to bring those different perspectives together. Not to point a finger at a guilty party, but to investigate where we can find each other and what shared vision is needed to prevent individual financial problems from growing into collective damage.”
What would you still like to share with the reader?
Emma: “What I especially want to share with the reader is that there are an enormous number of good initiatives. Among clients, judicial officers and debt collection, social organizations, and aid workers. At the same time, many of those initiatives are still fragmented. Everyone tries to improve something from their own role, while the real gain, in my opinion, lies in better connecting those efforts and formulating a shared vision.
For me, this also includes not unnecessarily setting interests against each other. Clients deliver a product or service and may expect to be paid for it. At the same time, they have influence over the way the customer journey is designed and the protection offered within it to consumers who are vulnerable or at risk of becoming so. Those two interests do not have to exclude each other.
We must also look critically at the context in which all those efforts take place. For me, the government is emphatically part of that. We can invest more and more in prevention, early detection, and consumer protection, but if rules remain complicated and financial temptations are easily accessible, we simultaneously put the results of all those good initiatives under pressure again.
For me, the next step therefore lies not in yet another separate initiative, but in more coherence. A shared vision on how we prevent payment problems, protect vulnerable consumers, and ensure that clients are paid in a healthy way for what they deliver.”
Bosveld Judicial Officers and Debt Collection is a Platinum Partner of Credit Expo 2026, which will take place on Thursday, November 5, at the 1931 Congress Centre in ‘s-Hertogenbosch. Would you like to know more about the services of Bosveld Debt Collection and Judicial Officers? Visit stand 8 or participate in theroundtable session “From individual debt to collective damage.” If you wish to participate, please send an email to marcel@creditexpo.nl stating RTS Bosveld Credit Expo 2026 and/or visit the presentation “From individual debt to collective damage” by Michiel Vos, facilitated by Bosveld Debt Collection and Judicial Officers. Click here to register for a free visit (provided you are part of the target group) to Credit Expo 2026.
Author: Marcel Wiedenbrugge


